
American News
Discordant Ukraine statements from Trump team leave allies anxious
Temporibus autem quibusdam et aut officiis debitis aut rerum necessitatibus saepe eveniet ut et voluptates repudiandae.


A cracked windscreen forced US Secretary of State Marco Rubio into a rapid U-turn as his plane, en route to the Munich Security Conference, had to turn back an hour into the flight.
America’s top diplomat, his senior officials and the travelling press returned to Andrews Air Force Base near Washington DC on Thursday night.
But despite the mid-air scare the news was already firmly elsewhere. In Europe, US Defence Secretary Pete Hegseth had stunned America’s allies with a speech setting out what many saw as a series of concessions Ukraine would have to make to sign any peace deal with Russia brokered by President Trump.
Hegseth said it was “unrealistic” to think Ukraine could win back its sovereign territory occupied by Russia, as was its demand for Nato membership, adding it was up to European and not US troops to keep the peace.
Critics, including some Republicans in Washington, castigated the speech, saying it gave away all of Ukraine’s leverage ahead of any negotiations. It was, they argued, a US capitulation to Russian President Vladimir Putin.
“It’s certainly an innovative approach to a negotiation to make very major concessions even before they have started,” said former Swedish Prime Minister Carl Bildt, who co-chairs the European Council on Foreign Relation, a think tank.
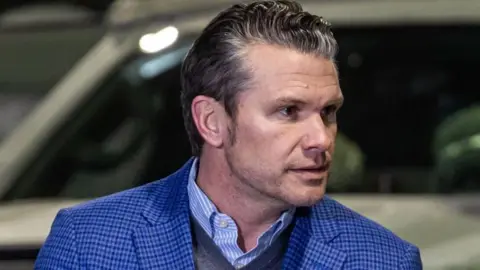
The following day, Hegseth wound back some of what he had said. He clarified that all options were in fact still on the table for Trump to use as leverage between Putin and Ukrainian President Volodymyr Zelensky.
“What he decides to allow or not allow is at the purview of the leader of the free world, President Trump,” said Hegseth. However he added he had been “simply pointing out realism” and rejected the idea he had offered any undue concessions to Moscow.
As for Rubio, the broken-down plane delayed his arrival in Munich, where his officials were briefing about his own priorities for the trip.
The United States would work for a “just and lasting peace” in which European countries would take the lead in creating a “durable security framework”, they said.
European leaders are expected to meet in Paris on Monday for urgent talks aimed at ensuring that their countries are fully involved in any Ukraine peace negotiations.
The US secretary of state’s position contained no trace of laying out limits for Ukraine in the way the defence secretary had done. Then, also in the German city, Vice-President JD Vance said the US could use “military tools of leverage” to compel Russia to do a deal, appearing to contradict Hegseth who had said no US troops would be deployed to Ukraine.
Later in the Oval Office, the fallout from Hegseth’s speech was put to President Trump – along with the commentary of a Republican senator who described it as a “rookie mistake”, like something a pro-Putin pundit could have written.
Had Trump been aware of what Hegseth was going to say? “Generally speaking, yeah, generally speaking I was,” said the president. “I’ll speak to Pete, I’ll find out,” he added.
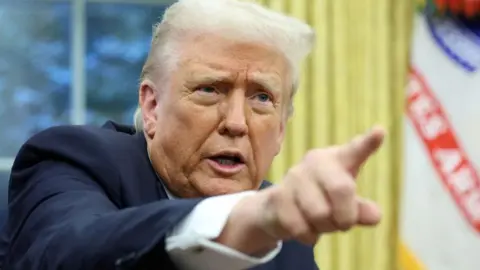
The three days of to and fro gave some of the first major insights into Trump’s evolving position on one of the most consequential issues he faces – Russia’s full-scale invasion of Ukraine and his vow to end the war – and also into how his administration is formulating and messaging its foreign policy.
On the substance, Hegseth’s speech – alongside Trump’s lengthy statement about an apparently warm phone call with Putin aimed at starting negotiations with Ukraine – sent shockwaves through European capitals, despite Hegseth’s attempts to row back.
“Any quick fix is a dirty deal,” said the European Union foreign policy chief Kaja Kallas of the prospect of a US-led deal with Russia that might leave Ukraine’s voice on the sidelines.
Then there is the question of the way US foreign policy under Trump was being communicated. What happened in Munich seemed to be partly an attempt by his senior officials to interpret and relay Trump’s positions, but that effort resulted in sometimes explosive and often contradictory statements – some of which were then partly diluted or reversed.
It is not yet clear how much this is the result of a new but ill-coordinated administration still clarifying its lines to take internally, as opposed to a deliberate feature of a presidency less concerned about officials freelancing with rhetoric, even if it sows some confusion, so long as they remain loyal to his final word.
Trump’s first term saw a series of high-profile sackings or resignations of top officials who contradicted or disagreed with him, including three national security advisers, two defence secretaries and a secretary of state.
This time around, his appointments have been characterised more frequently by a willingness to show loyalty. Pete Hegseth, who had no previous experience running a military or government or agency, was a Fox News weekend presenter and former National Guard major who aligns strongly with Trump’s thinking and agenda.
His appointment was highly contested and scraped through its confirmation process with three Republican senators voting against him, seeing the result tied 50-50 with JD Vance casting the tie-breaking vote.
As Trump said himself this week he was “okay” with the idea of taking Ukraine joining Nato off the negotiating table, calling it “not practical”.
Hegseth’s comments were hardly out of line with the president’s position – rather they were an amplification of it to an audience anxious to shore up Ukraine’s negotiating position not weaken it.
The challenge for those affected is that the precise position of US foreign policy is having to be divined. One of its features is uncertainty. This may well be deliberate – Donald Trump using the “madman” theory of foreign relations – often attributed to former Republican President Richard Nixon.
This suggests that being powerful but unpredictable is a way to make allies stay close while coercing adversaries. It would also explain a sense of his own officials going rogue but within the parameters of Trump’s broadly known positions.
But as this theory’s name suggests, it also carries considerable risks of mistakes or miscalculation in an already violent and uncertain world.
Trump’s recent proposals for Gaza – emptying it of its Palestinian population to build the “Riviera of the Middle East” under US ownership – were similarly permeated with confusion and contradiction.
While his officials appeared to try to correct some of what he set out – as only “temporary relocation” for example –Trump later doubled down saying it would in fact be “permanent” with no right of return.
As for Rubio – who wants the state department be the most influential government agency when it comes to Trump’s decision-making – his colleagues’ comments at Munich were already overshadowing his own.
His smaller, replacement plane finally landed in Europe – windscreen intact but without the press pool on board, while most of the headlines were also going elsewhere.
Taken From BBC News







Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : Watching television in Michigan, I hear one election advertisement after another describe an opposing candidate as dangerous. The names change, the parties change, but the warning remains. Across the advertisements I encounter, nobody seems to be spared. If these campaigns are to be believed, Americans are preparing to send dangerous people into the House and Senate. What, then, will become of the country and the families whose future these representatives will decide?
Before coming to the United States, I associated such relentless mudslinging largely with developing countries. In Pakistan, I had watched political differences descend into insults, allegations of betrayal and character assassination. I expected greater restraint from an established democracy. Instead, I have encountered a familiar practice supported by an exceptionally powerful advertising industry.
One candidate appears as a threat to public safety, another as a servant of wealthy interests, another as fundamentally dishonest. Then the next commercial reverses the accusation. The person presented as the country’s protector becomes its supposed danger when the opponent’s advertisement begins.
The audience faces an unsettling dilemma. Accept these portrayals and distrust the people seeking office; reject them and question the honesty of those financing the messages. Either response can weaken confidence in politics. A candidate may win an election while helping destroy the credibility needed to govern afterwards.
The attacks extend into debates, rallies and social media. The Hill’s October 25 account of seven particularly bitter campaign moments documents exchanges across states and parties. In Ohio, Vivek Ramaswamy’s campaign featured Amy Acton’s estranged mother calling her daughter a liar. In Texas, attacks on James Talarico targeted his masculinity, former veganism and supposed sexuality. Such personal ridicule tells voters little about governing ability.
In Georgia, Jon Ossoff called Mike Collins a bigot and invoked Nazi imagery over his office’s staffing, amid controversy about antisemitic posts by people connected to Collins. Collins condemned racism and antisemitism. In Maine, Troy Jackson told Susan Collins to “shut up” after she attributed a debate interruption to one of his supporters; Jackson denied knowing the protester.
Michigan provided examples within and between parties. Mike Rogers sought to associate Abdul El-Sayed with the Muslim Brotherhood, which El-Sayed disavowed. During the Democratic primary, Haley Stevens faced online mockery of her appearance and voice. El-Sayed himself disparaged her speaking ability before later urging supporters to stop personal mockery and focus on issues.
In Ohio’s Senate contest, Sherrod Brown and Jon Husted each invoked the other’s donations from people linked, closely or loosely, to Jeffrey Epstein. FactCheck.org identified omissions in both presentations. Financial relationships merit scrutiny, but an insinuation of shared guilt can travel much further than the evidence supporting it.
These incidents are not interchangeable. Criticism of documented misconduct differs from religious insinuation; an insult differs from a criminal accusation. Nevertheless, responsibility for truthful, proportionate campaigning belongs to every party. The standard must follow the conduct, whoever engages in it.
Nor should genuine misconduct disappear behind complaints about mudslinging. The House Ethics Committee found inappropriate conduct by Republican Chuck Edwards towards female staff members and announced a review of allegations involving Republican Max Miller, who denies abuse accusations. Democratic politician Sheila Cherfilus-McCormick has faced charges over the alleged diversion of $5 million in disaster funds, including money allegedly used for campaigning. She has denied wrongdoing.
An ethics finding, an investigation and a criminal charge represent different stages of accountability. None should be misrepresented. Parties must resist both manufactured disgrace and the protection of misconduct. Faster, fairer investigations, safeguards against retaliation and clear public findings would help voters distinguish substantiated concerns from electoral insinuation.
The resources shaping public impressions are enormous. AdImpact data analysed by the Wesleyan Media Project recorded Senate advertising expenditure of $56.95 million in Michigan, $90.21 million in Ohio and $112.58 million in Texas between September 8 and 27. Outside groups supplied approximately 69, 77 and 83 percent respectively. These totals cover all advertising, not exclusively attacks, but demonstrate the scale of the contest for public attention.
Corporate interests, wealthy donors and advocacy organisations all deserve scrutiny. AIPAC and its affiliated United Democracy Project belong within that examination, alongside other influential groups. Voters should know who pays for political messages, what interests sponsors advance and whether candidates’ commitments serve their constituents.
The law must also be described accurately. Foreign governments cannot lawfully finance American election campaigns. Corporations generally cannot contribute treasury funds directly to federal candidates, although eligible corporate funding can support independent spending through super PACs. Foreign-agent registration does not override election-finance restrictions. Enforcing these rules and improving transparency are essential to meaningful public oversight.
My experience in public service suggests a troubling contrast. Military personnel, bureaucrats, lawyers and corporate leaders often protect their professions’ standing despite internal disagreements. Politicians repeatedly damage their collective reputation for individual advantage. Yet professional solidarity must never become a shield against accountability. What deserves protection is the integrity of public service, not immunity for those who abuse it.
Both major parties should adopt a public campaign code with meaningful internal consequences. Serious factual accusations should carry accessible evidence. Religious identity, appearance and family vulnerability should not become substitutes for evaluating public conduct. False claims should receive prominent corrections, and candidates should repudiate misleading outside advertisements supporting them.
Criticism cannot reasonably wait for a criminal conviction. Journalism and public scrutiny often uncover wrongdoing before courts act. The necessary discipline is accuracy: distinguish association from complicity, allegations from findings, and policy disagreement from hostility towards the nation. Congress should strengthen disclosure and enforcement within constitutional protections for political speech.
A vibrant democracy should continually refine its practices. Elections should test whether candidates understand the problems confronting their communities, states and country. Integrity is indispensable, but voters must also assess competence, judgement and the ability to turn promises into results. A clean reputation alone does not establish the capacity to govern.
Candidates should explain what they intend to accomplish, what it will cost, which powers their office actually provides and when citizens can expect progress. Plans for affordable healthcare, reliable infrastructure, safer neighbourhoods and stronger public services should include measurable goals and realistic deadlines. Legislators should specify the laws, funding and oversight they will pursue rather than promise outcomes they cannot deliver alone.
That is the standard a mature democracy should set for itself and offer to the world. Families deserve representatives who make their country stronger, safer and more prosperous, and who can be judged against commitments made before election day.
Calling every opponent dangerous cannot answer those needs. America’s candidates should tell voters how they will solve the country’s problems and accept responsibility for the results. The lasting measure of an election is not how thoroughly its contestants destroy one another, but how well its winners serve the people.
Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : For households, however, both principal and interest still have to be found each month. Principal repayment may build ownership, but it cannot simultaneously buy groceries or meet an emergency. The family lives through cash flow, not accounting classifications.
Then comes the subscription economy. EMARKETER forecast $46.4 billion in U.S. paid retail membership fees for 2025. Shopping clubs sell access to savings; software sells continued access to tools; streaming platforms sell entertainment; newspapers and magazines sell information; security businesses sell monitoring and reassurance.
Our research identified approximately $56.66 billion in separately reported worldwide subscription revenue across just seven companies for their annual periods labelled 2025: Adobe, Disney’s entertainment streaming business, SiriusXM, Dropbox, Peloton, The New York Times’ digital products and Duolingo. Spotify separately reported €15.35 billion in Premium revenue.
Netflix reported $45.18 billion in worldwide revenue, predominantly from memberships but also including advertising and other sources. Amazon’s $49.62 billion subscription-services category combined Prime and other digital subscriptions. Newspapers beyond the Times, magazines, tabloids, other apps and private platforms add further charges. OnlyFans illustrates another variation: approximately $7.2 billion in worldwide customer payments in fiscal 2024 generated about $1.41 billion in platform revenue, with payments encompassing more than subscription fees.
These figures cannot honestly be added into a single measure of American household extraction. They cover different countries, reporting periods and revenue definitions, and some overlap. Their significance lies in the breadth of the business model: an increasing range of activities carries a continuing payment obligation.
The consequences of this structure became personal when my family moved from Pakistan to Michigan. In Pakistan, I could educate my children, meet household expenses, pay my dues and still save for the future. In the United States, several members of my family work, savings accumulated over a lifetime continue to supplement our earnings, and the month still ends with little room to breathe. The American dollar is stronger. Our household’s financial security feels weaker.
Since moving to the United States in 2025, I have experienced how a higher-earning economy can leave a working household with less financial breathing room.
After a career in public service, my income in Pakistan provided purchasing power that its dollar equivalent—roughly $1,500 to $1,800 a month by my recollection—fails to convey. I could meet an education bill of approximately Rs100,000 for my two children, buy groceries, obtain medical care and maintain a reserve for unforeseen expenses. Over the years, I also built assets intended to protect my wife, my children and myself.
Today, my wife works two jobs. I work, and our 18-year-old daughter and 16-year-old son also work. Yet the combined effort of our household, supplemented by savings brought from Pakistan, has not produced the financial comfort we expected.
Groceries, by my estimate, account for only about 10 to 15 percent of our spending. Our son attends public school, while our daughter’s education is being financed through a loan. That loan postpones a burden; it does not make education free. The remaining income is absorbed by housing, utilities, transportation, insurance, debt payments, memberships and other recurring charges. We are working to keep the account current, while the future waits.
My experience cannot represent every Pakistani or American household. My professional standing and accumulated assets mattered in Pakistan; migration created new costs in America. Pakistan’s lower-paid workers face severe hardship, and affordable care is neither universally available nor consistently adequate. But those differences do not invalidate the question our experience raises: why does a family require so many earners merely to maintain an ordinary life in a wealthy country?
My experience in Pakistan was different. Many routine medical consultations, medicines and vehicle repairs could be paid from ordinary savings. Lower wages and operating costs help explain that difference; it cannot all be attributed to corporate conduct. Still, the practical consequence matters: an affordable repair lets a household solve a problem directly. An unaffordable repair can turn the same problem into a financing agreement, a protection contract or another claim on future income.
An optional streaming service is not equivalent to necessary medical treatment. Cancelling subscriptions can help a budget. But cancelling entertainment cannot repair an unaffordable housing market, make a car-dependent commute disappear or bring hospital prices within reach. Advice to economize becomes inadequate when it treats small discretionary charges as the main explanation for structural costs.
Donald Trump has recognized the political force of that pressure. In January 2026, his administration proposed a healthcare framework addressing drug prices, insurance accountability, middlemen and price transparency. Those proposals acknowledge that Americans face serious affordability problems. Announcing them, however, is different from delivering household relief.
The test of Trump’s economic leadership must be the money and security left with families after essential bills are paid. Corporate growth and rising asset values cannot substitute for that test. If several members of a household must work while long-accumulated savings are consumed simply to remain current, declarations of prosperity do not describe that household’s reality.
Discipline must begin where costs are largest: healthcare pricing, housing supply and financing, transportation, insurance and expensive consumer debt. Competition rules should confront abusive market power. Medical prices should be understandable before treatment where feasible. Insurance should provide clear coverage and fair claims handling. Repair markets should offer affordable alternatives. Subscription cancellation should be as straightforward as enrolment. Public transport should make employment possible without multiplying vehicle costs.
These reforms would preserve useful services while challenging prices and practices that leave families dependent and financially exposed. The objective should be a household capable of saving, choosing and planning.
I did not bring a lifetime of savings to America merely to watch it disappear between payment deadlines. I came with the hope that work would improve our security and give our children a stronger future.
A prosperous country should allow that hope to survive the monthly bills. When parents work, teenagers work and savings still shrink, the measure of success must extend beyond the balance sheets of the companies collecting the payments. The American promise must be judged by what remains in the household—and what that household can still hope to become.
Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : Across America, millions of households are working to exhaustion while banks, insurers, lenders and corporate platforms collect their share before the family can put anything aside. The mortgage falls due. The car payment follows. Insurance premiums, utility bills, credit-card interest, protection plans and subscriptions arrive in succession. By the time the household has paid for the right to remain housed, mobile, connected and protected, little may remain for savings, a child’s education or a secure retirement. Work continues; financial freedom retreats.
At the other end of these payment chains, wealth accumulates on a scale almost impossible for an ordinary wage earner to imagine. The contrast is stark: families calculate which bill can wait, while the fortunes at the top expand by billions. America has become extraordinarily successful at creating immense private fortunes. Its greater failure is allowing so many people who sustain that prosperity to live with persistent financial insecurity.
Forbes’ March 2026 ranking placed 15 of the world’s 20 richest people in the United States. Its September assessment valued America’s 400 wealthiest people at a combined $8 trillion, up from $6.6 trillion a year earlier. The richest 20 Americans alone held approximately $4 trillion. Those estimates measure assets, not cash taken directly from households, but they reveal the extraordinary concentration of economic power at the summit.
Meanwhile, the Census Bureau counted 34.5 million Americans below the official poverty line in 2025, or 10.2 percent of the population. Its broader Supplemental Poverty Measure, which accounts for taxes, benefits and expenses including medical and work costs, put poverty at 13.1 percent. Financial insecurity extends beyond these thresholds. A household can earn too much to be classified as poor and still have too little left after essential bills to withstand illness, unemployment or a major repair.
That is the dividing line this article examines: the difference between earning an income and retaining enough of it to build a life. The Federal Reserve found that 91 percent of adults were concerned about prices in 2025. Only 63 percent said they could cover a $400 emergency entirely with cash or its equivalent, and 26 percent reported skipping medical care because of cost. A wealthy national economy can coexist with deeply insecure household budgets.
The pressure is cumulative. Housing ties income to rent or a long mortgage. Employment may require a car, which brings financing, insurance, fuel and repairs. High medical prices make protection indispensable, yet insurance itself requires premiums and may leave further out-of-pocket bills. Credit covers the shortfall and creates another interest charge. Subscriptions and service contracts then add smaller claims on what remains. Each institution sees its own transaction; the family must survive their combined demand.
The question is how much income a household can retain after buying the necessities of participation in American life. When essential services become increasingly expensive and access depends on continuing payments, corporate revenue can rise while the people supplying that revenue lose their capacity to save.
Housing is the first claim on income. According to the U.S. Census Bureau, median monthly owner costs for households with a mortgage reached $2,035 in 2024, including selected costs such as insurance, taxes and utilities. Median gross rent was $1,487. These are national figures; individual households can face much higher bills. Before a family purchases food or saves for a child, shelter has already taken a substantial share of its earnings.
Transportation creates another chain of obligations. Where we live and work in Michigan, available public transport does not adequately connect our family’s different workplaces and schedules. Four people travelling in different directions can create pressure for several vehicles. Each brings some combination of a purchase payment, fuel, registration, repairs and insurance. Transportation becomes part of the cost of holding a job.
Michigan requires no-fault insurance for vehicles driven legally. A lender may also require additional protection for a financed car. Homeowners insurance is generally a mortgage condition, while life insurance, extended warranties and shopping memberships are ordinarily optional. These distinctions matter. Nevertheless, the household experiences the cumulative bill, regardless of whether each component originates in legislation, a lending contract or a personal decision.
The Bureau of Labor Statistics offers a revealing national comparison. In 2024, housing accounted for 33.4 percent of average consumer expenditure and transportation another 17 percent. Together, they absorbed just over half of spending. Food accounted for 12.9 percent. Our experience of groceries being a relatively small part of the pressure is therefore entirely plausible: the larger burdens often arrive before the shopping begins.
Healthcare makes that pressure more formidable. KFF found that average annual premiums for employer-sponsored family health coverage reached $26,993 in 2025. Workers contributed $6,850 on average, with employers paying the balance. The entire premium does not come directly out of the worker’s paycheck, but the employer’s contribution remains part of the cost of employing that worker.
Even after coverage is purchased, deductibles, copayments and uncovered services may remain. Dental and vision benefits are frequently arranged separately. A family can therefore pay repeatedly for protection and still face a significant bill when it actually needs treatment.
Insurance provides real protection against losses that savings alone may not cover. A year without a claim does not mean the protection had no value. The deeper problem is that when treatment, repairs or replacement become prohibitively expensive, households become increasingly dependent on intermediaries to afford the underlying service. Lowering the price of care would strengthen both insured families and those struggling to obtain coverage.
The scale of the American financial machinery is enormous. The NAIC’s report covering 2024 recorded 6,228 domestic insurance companies and approximately $3.65 trillion in premiums and deposits. That figure includes commercial business, annuities and deposit-type funds; it is neither household spending alone nor industry profit. Yet it demonstrates how much economic activity passes through institutions selling financial protection.
Protection is then sold in additional layers. Industry estimates put U.S. home-warranty providers at 78 businesses and $4.3 billion in revenue in 2024. Auto extended-warranty providers numbered approximately 287 in 2024, with their market estimated at $22 billion in 2025. Appliance, electronics and phone protection plans extend the model further. Their prices may appear modest beside a mortgage, but each is another recurring commitment competing with savings.
Credit supplies relief today by reserving part of tomorrow’s earnings. At the end of 2025, 4,336 FDIC-insured banks and savings institutions and 4,287 federally insured credit unions operated in the United States. Their combined reported net income was approximately $314.4 billion. Their activities include business lending and other services, so this cannot be presented as profit extracted exclusively from households. But it establishes the scale of the institutions through which families finance major purchases and manage shortfalls.
Mortgages require the same accounting discipline. The latest official dataset covered 4,782 institutions reporting 2025 mortgage activity. The Mortgage Bankers Association’s October 2026 forecast put that year’s single-family mortgage originations at approximately $2.1 trillion. The principal advanced is not lenders’ revenue. Interest, fees, servicing and loan-sale income are the relevant earnings streams. United Wholesale Mortgage, for example, originated $163.4 billion in loans in 2025 and reported $3.16 billion in revenue.


The Dawn of Physical, Intimacy and Consciousness Intelligence

Tehran’s Diplomatic Bombshell

Netanyahu’s Electoral Setback: Will Israel Choose War or Diplomacy?

New Chapter for Dragon Boating in Punjab and Khyber Pakhtunkhwa Provincial associations officially set up with sights locked on national competitions and international representation.

South Korea’s Yoo Useong Steps Onto the Global Strongman Stage as World Strongman Federation Professional Athlete

A Survey of Mata-E-Zeest


-
 Pakistan News3 weeks ago
New Chapter for Dragon Boating in Punjab and Khyber Pakhtunkhwa Provincial associations officially set up with sights locked on national competitions and international representation.
-
 Sports5 months ago
South Korea’s Yoo Useong Steps Onto the Global Strongman Stage as World Strongman Federation Professional Athlete
-
 Art & Culture1 year ago
A Survey of Mata-E-Zeest
-

 Europe News2 years ago
Chaos and unproven theories surround Tates’ release from Romania
-

 American News2 years ago
Trump expands exemptions from Canada and Mexico tariffs
-

 Art & Culture2 years ago
Will Snow White be a ‘victim of its moment’? How the Disney remake became 2025’s most divisive film
-

 American News2 years ago
Trump Expels Zelensky from the White House
-

 Entertainment2 years ago
Champions Trophy: Pakistan aim to defend coveted title as historic tournament kicks off today