
American News
Why is Trump a Dictator?

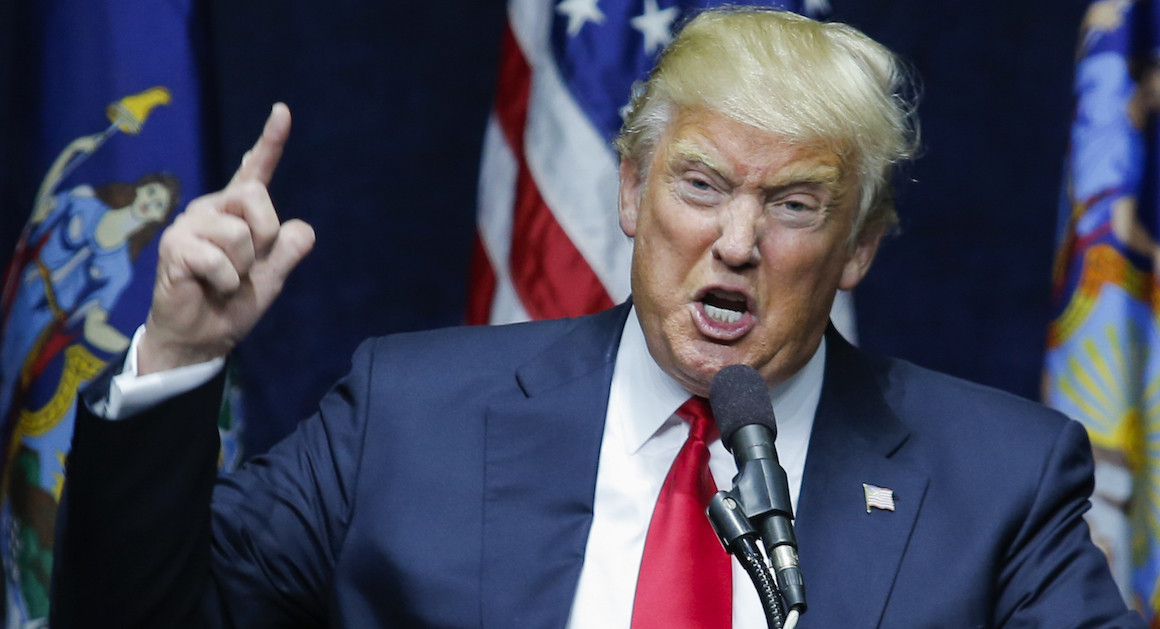
Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : Trump was elected legitimately, and his supporters deserve representation. But every president governs a country larger than his constituency. Congress, courts, journalists and universities have responsibilities independent of presidential approval. Treating their independence as an obstacle to overcome carries authoritarian implications.
Retired federal judge Mark Wolf’s resignation provides a powerful framework for understanding these concerns. A Reagan appointee with four decades on the bench and approximately fifty years in public service, Wolf relinquished his lifetime appointment in November 2025 has spoken now.
He believed the administration’s assaults on equal justice had made silence intolerable. He accused Trump of directing the Justice Department to pursue perceived political enemies while failing to investigate possible corruption involving presidential allies and people enriching the president and his family.
Wolf also condemned Trump’s practice of calling judges corrupt and demanding their impeachment after unfavorable rulings, warning that such attacks undermine confidence in judicial independence.
He said the president’s inflammatory comments had coincided with death threats against judges and growing anxiety for their families. Citing reports that court orders were not always being properly obeyed, Wolf warned that judicial decisions lose their protective force when the executive can disregard them.
At Brandeis, he emphasized collective civic action and the ability of young people to hold their elders to higher standards. His warning places a fundamental question: can the institutions entrusted with enforcing the law still hold the president and those closest to him accountable?
The Iran war exposes the consequences of concentrated executive power. In his May 1, 2026 letter to Congress, Trump declared that the hostilities beginning on February 28 “have terminated,” citing the April 7 ceasefire. The administration relied on that position to argue that the War Powers Resolution’s 60-day deadline no longer required congressional authorization. Yet military action continued into September without specific congressional authorization.
Trump’s treatment of foreign governments reveals a troubling preference for coercion over consent, extending from adversaries to longstanding allies. American forces seized Venezuela’s Nicolás Maduro in January 2026 and transported him to New York to face criminal charges, which he denied; the operation prompted the United Nations secretary-general to question its conformity with international law.
Trump subsequently threatened a takeover of Cuba. He also vowed to use economic pressure to make Canada America’s 51st state, pursued control of Greenland, and threatened additional tariffs on eight European countries over their opposition to that ambition.
Separately, his 2025 trade agreement imposed a 15 percent tariff on most European Union goods. Relations deteriorated further when he called NATO allies “cowards” for withholding support for the Iran war, while European governments questioned involvement in a conflict they had not chosen.
Trump banned CNN, MS NOW and Politico from White House grounds after denouncing their coverage as “fake news,” subsequently arguing that their reporting threatened national security. The administration cited stories concerning White House security infrastructure and an alleged leak investigation; the outlets argued that they were being punished for their editorial content. This illustrates the danger of making journalistic access dependent on presidential approval. Journalists serve the public by asking uncomfortable questions, and penalizing unfavorable coverage undermines citizens’ ability to scrutinize their government.
Trump’s crackdown on immigrants brought an expanded federal enforcement presence into communities and military support onto American streets. In Los Angeles, Trump deployed National Guard troops and Marines over state and local objections. Immigration raids and the deployments fueled demonstrations that spread to other major cities, intensifying confrontation between Washington, local authorities and residents. The human consequences extended beyond those targeted for deportation. Federal immigration officers fatally shot American citizens Renee Good and Alex Pretti in Minneapolis, provoking investigations and nationwide outrage. Separately, the death of Cuban immigrant Geraldo Lunas Campos in immigration detention was classified as a homicide by the medical examiner.
Trump’s stock market manipulation extended to amass a lot of wealth for his closet family members, close associates and Trump linked companies. In August, Senator Elizabeth Warren and Representative Robert Garcia cited more than 17,000 stock trades worth up to $1.56 billion across the periods examined, questioning transactions overlapping with government decisions.
Family ventures broaden these concerns. A Senate resolution introduced in February challenged approval of advanced artificial-intelligence chip exports to the United Arab Emirates following a reported $500 million UAE-linked investment in World Liberty Financial. The sequence does not prove an exchange of money for favors, but demands examination of whether commercial interests influenced national-security decisions.
Congressional investigators also questioned federal support for Vulcan Elements, a company backed by Donald Trump Jr.’s investment firm, alleging White House intervention. Separately, PBS reported that Jared Kushner’s Affinity Partners disclosed more than $6.1 billion in assets while he had resumed diplomatic work. Those assets are not his personal fortune. The concern is whether financial relationships influence public decisions or diplomatic access attracts private business.
The accumulation of wealth around Trump’s presidency spans both administrations and raises serious questions about the separation of public power from private interests. During his first term, Jared Kushner and Ivanka Trump reported between $172 million and $640 million in outside income across disclosure periods that also included some earnings before their appointments. By September 2025, Forbes estimated the family’s combined wealth at approximately $10 billion—nearly double its value at the preceding election—including $7.3 billion for Donald Trump, $750 million for Eric, $500 million for Donald Jr., $150 million for Barron, $1 billion for Kushner and $100 million for Ivanka. Trump himself disclosed more than $1.4 billion in cryptocurrency income for 2025.
Kushner’s Affinity Partners reported more than $6.1 billion in managed assets, while a congressional inquiry cited growth at Donald Jr.’s 1789 Capital from approximately $150 million to over $3 billion. That inquiry highlighted portfolio company Vulcan Elements, whose valuation reportedly rose from approximately $200 million to $2 billion after receiving a $620 million federal loan and a $50 million grant.
The administration’s approach to universities carries longer-term consequences. In September 2025, a federal judge ruled that approximately $2.2 billion in Harvard research grants had been unlawfully terminated. The administration cited antisemitism; the court found unlawful retaliation and procedural failures. Universities must confront discrimination, but scientific funding should never become an instrument of political conformity. Interrupting research risks discoveries whose value emerges over decades.
The dismantling of USAID by Trump weakened an institution that combined humanitarian assistance with American diplomatic influence. Before Trump’s second term, the agency employed more than 10,000 people, maintained over 60 country and regional missions, and provided assistance to approximately 130 countries with budget allocation of over $40 billion. On July 1, 2025, the agency ceased implementing foreign assistance sacrificing accumulated expertise, dependable partnerships and goodwill built over decades.
These actions and behaviors by Trump are less democratic in character and closer to dictatorial conduct. This disposition is particularly troubling because the American constitutional system is founded on a commitment to democracy and resistance to unchecked power.
In November’s midterm elections, the people of the United States will once again deliver their verdict. Support for Trump’s political allies would strengthen his claim to public endorsement; their rejection would signal a demand for democratic accountability and resistance to dictatorial behavior, even though he is not a dictator in the fullest sense.
Americans are outspoken and capable of distinguishing right from wrong. History shows that, although their tolerance is considerable, they can act decisively when they conclude that change is necessary to restore constitutional balance. Let us hope that sound judgment prevails and that the Trump administration changes course, returning to the democratic values on which the United States was founded.







Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : For households, however, both principal and interest still have to be found each month. Principal repayment may build ownership, but it cannot simultaneously buy groceries or meet an emergency. The family lives through cash flow, not accounting classifications.
Then comes the subscription economy. EMARKETER forecast $46.4 billion in U.S. paid retail membership fees for 2025. Shopping clubs sell access to savings; software sells continued access to tools; streaming platforms sell entertainment; newspapers and magazines sell information; security businesses sell monitoring and reassurance.
Our research identified approximately $56.66 billion in separately reported worldwide subscription revenue across just seven companies for their annual periods labelled 2025: Adobe, Disney’s entertainment streaming business, SiriusXM, Dropbox, Peloton, The New York Times’ digital products and Duolingo. Spotify separately reported €15.35 billion in Premium revenue.
Netflix reported $45.18 billion in worldwide revenue, predominantly from memberships but also including advertising and other sources. Amazon’s $49.62 billion subscription-services category combined Prime and other digital subscriptions. Newspapers beyond the Times, magazines, tabloids, other apps and private platforms add further charges. OnlyFans illustrates another variation: approximately $7.2 billion in worldwide customer payments in fiscal 2024 generated about $1.41 billion in platform revenue, with payments encompassing more than subscription fees.
These figures cannot honestly be added into a single measure of American household extraction. They cover different countries, reporting periods and revenue definitions, and some overlap. Their significance lies in the breadth of the business model: an increasing range of activities carries a continuing payment obligation.
The consequences of this structure became personal when my family moved from Pakistan to Michigan. In Pakistan, I could educate my children, meet household expenses, pay my dues and still save for the future. In the United States, several members of my family work, savings accumulated over a lifetime continue to supplement our earnings, and the month still ends with little room to breathe. The American dollar is stronger. Our household’s financial security feels weaker.
Since moving to the United States in 2025, I have experienced how a higher-earning economy can leave a working household with less financial breathing room.
After a career in public service, my income in Pakistan provided purchasing power that its dollar equivalent—roughly $1,500 to $1,800 a month by my recollection—fails to convey. I could meet an education bill of approximately Rs100,000 for my two children, buy groceries, obtain medical care and maintain a reserve for unforeseen expenses. Over the years, I also built assets intended to protect my wife, my children and myself.
Today, my wife works two jobs. I work, and our 18-year-old daughter and 16-year-old son also work. Yet the combined effort of our household, supplemented by savings brought from Pakistan, has not produced the financial comfort we expected.
Groceries, by my estimate, account for only about 10 to 15 percent of our spending. Our son attends public school, while our daughter’s education is being financed through a loan. That loan postpones a burden; it does not make education free. The remaining income is absorbed by housing, utilities, transportation, insurance, debt payments, memberships and other recurring charges. We are working to keep the account current, while the future waits.
My experience cannot represent every Pakistani or American household. My professional standing and accumulated assets mattered in Pakistan; migration created new costs in America. Pakistan’s lower-paid workers face severe hardship, and affordable care is neither universally available nor consistently adequate. But those differences do not invalidate the question our experience raises: why does a family require so many earners merely to maintain an ordinary life in a wealthy country?
My experience in Pakistan was different. Many routine medical consultations, medicines and vehicle repairs could be paid from ordinary savings. Lower wages and operating costs help explain that difference; it cannot all be attributed to corporate conduct. Still, the practical consequence matters: an affordable repair lets a household solve a problem directly. An unaffordable repair can turn the same problem into a financing agreement, a protection contract or another claim on future income.
An optional streaming service is not equivalent to necessary medical treatment. Cancelling subscriptions can help a budget. But cancelling entertainment cannot repair an unaffordable housing market, make a car-dependent commute disappear or bring hospital prices within reach. Advice to economize becomes inadequate when it treats small discretionary charges as the main explanation for structural costs.
Donald Trump has recognized the political force of that pressure. In January 2026, his administration proposed a healthcare framework addressing drug prices, insurance accountability, middlemen and price transparency. Those proposals acknowledge that Americans face serious affordability problems. Announcing them, however, is different from delivering household relief.
The test of Trump’s economic leadership must be the money and security left with families after essential bills are paid. Corporate growth and rising asset values cannot substitute for that test. If several members of a household must work while long-accumulated savings are consumed simply to remain current, declarations of prosperity do not describe that household’s reality.
Discipline must begin where costs are largest: healthcare pricing, housing supply and financing, transportation, insurance and expensive consumer debt. Competition rules should confront abusive market power. Medical prices should be understandable before treatment where feasible. Insurance should provide clear coverage and fair claims handling. Repair markets should offer affordable alternatives. Subscription cancellation should be as straightforward as enrolment. Public transport should make employment possible without multiplying vehicle costs.
These reforms would preserve useful services while challenging prices and practices that leave families dependent and financially exposed. The objective should be a household capable of saving, choosing and planning.
I did not bring a lifetime of savings to America merely to watch it disappear between payment deadlines. I came with the hope that work would improve our security and give our children a stronger future.
A prosperous country should allow that hope to survive the monthly bills. When parents work, teenagers work and savings still shrink, the measure of success must extend beyond the balance sheets of the companies collecting the payments. The American promise must be judged by what remains in the household—and what that household can still hope to become.
Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : Across America, millions of households are working to exhaustion while banks, insurers, lenders and corporate platforms collect their share before the family can put anything aside. The mortgage falls due. The car payment follows. Insurance premiums, utility bills, credit-card interest, protection plans and subscriptions arrive in succession. By the time the household has paid for the right to remain housed, mobile, connected and protected, little may remain for savings, a child’s education or a secure retirement. Work continues; financial freedom retreats.
At the other end of these payment chains, wealth accumulates on a scale almost impossible for an ordinary wage earner to imagine. The contrast is stark: families calculate which bill can wait, while the fortunes at the top expand by billions. America has become extraordinarily successful at creating immense private fortunes. Its greater failure is allowing so many people who sustain that prosperity to live with persistent financial insecurity.
Forbes’ March 2026 ranking placed 15 of the world’s 20 richest people in the United States. Its September assessment valued America’s 400 wealthiest people at a combined $8 trillion, up from $6.6 trillion a year earlier. The richest 20 Americans alone held approximately $4 trillion. Those estimates measure assets, not cash taken directly from households, but they reveal the extraordinary concentration of economic power at the summit.
Meanwhile, the Census Bureau counted 34.5 million Americans below the official poverty line in 2025, or 10.2 percent of the population. Its broader Supplemental Poverty Measure, which accounts for taxes, benefits and expenses including medical and work costs, put poverty at 13.1 percent. Financial insecurity extends beyond these thresholds. A household can earn too much to be classified as poor and still have too little left after essential bills to withstand illness, unemployment or a major repair.
That is the dividing line this article examines: the difference between earning an income and retaining enough of it to build a life. The Federal Reserve found that 91 percent of adults were concerned about prices in 2025. Only 63 percent said they could cover a $400 emergency entirely with cash or its equivalent, and 26 percent reported skipping medical care because of cost. A wealthy national economy can coexist with deeply insecure household budgets.
The pressure is cumulative. Housing ties income to rent or a long mortgage. Employment may require a car, which brings financing, insurance, fuel and repairs. High medical prices make protection indispensable, yet insurance itself requires premiums and may leave further out-of-pocket bills. Credit covers the shortfall and creates another interest charge. Subscriptions and service contracts then add smaller claims on what remains. Each institution sees its own transaction; the family must survive their combined demand.
The question is how much income a household can retain after buying the necessities of participation in American life. When essential services become increasingly expensive and access depends on continuing payments, corporate revenue can rise while the people supplying that revenue lose their capacity to save.
Housing is the first claim on income. According to the U.S. Census Bureau, median monthly owner costs for households with a mortgage reached $2,035 in 2024, including selected costs such as insurance, taxes and utilities. Median gross rent was $1,487. These are national figures; individual households can face much higher bills. Before a family purchases food or saves for a child, shelter has already taken a substantial share of its earnings.
Transportation creates another chain of obligations. Where we live and work in Michigan, available public transport does not adequately connect our family’s different workplaces and schedules. Four people travelling in different directions can create pressure for several vehicles. Each brings some combination of a purchase payment, fuel, registration, repairs and insurance. Transportation becomes part of the cost of holding a job.
Michigan requires no-fault insurance for vehicles driven legally. A lender may also require additional protection for a financed car. Homeowners insurance is generally a mortgage condition, while life insurance, extended warranties and shopping memberships are ordinarily optional. These distinctions matter. Nevertheless, the household experiences the cumulative bill, regardless of whether each component originates in legislation, a lending contract or a personal decision.
The Bureau of Labor Statistics offers a revealing national comparison. In 2024, housing accounted for 33.4 percent of average consumer expenditure and transportation another 17 percent. Together, they absorbed just over half of spending. Food accounted for 12.9 percent. Our experience of groceries being a relatively small part of the pressure is therefore entirely plausible: the larger burdens often arrive before the shopping begins.
Healthcare makes that pressure more formidable. KFF found that average annual premiums for employer-sponsored family health coverage reached $26,993 in 2025. Workers contributed $6,850 on average, with employers paying the balance. The entire premium does not come directly out of the worker’s paycheck, but the employer’s contribution remains part of the cost of employing that worker.
Even after coverage is purchased, deductibles, copayments and uncovered services may remain. Dental and vision benefits are frequently arranged separately. A family can therefore pay repeatedly for protection and still face a significant bill when it actually needs treatment.
Insurance provides real protection against losses that savings alone may not cover. A year without a claim does not mean the protection had no value. The deeper problem is that when treatment, repairs or replacement become prohibitively expensive, households become increasingly dependent on intermediaries to afford the underlying service. Lowering the price of care would strengthen both insured families and those struggling to obtain coverage.
The scale of the American financial machinery is enormous. The NAIC’s report covering 2024 recorded 6,228 domestic insurance companies and approximately $3.65 trillion in premiums and deposits. That figure includes commercial business, annuities and deposit-type funds; it is neither household spending alone nor industry profit. Yet it demonstrates how much economic activity passes through institutions selling financial protection.
Protection is then sold in additional layers. Industry estimates put U.S. home-warranty providers at 78 businesses and $4.3 billion in revenue in 2024. Auto extended-warranty providers numbered approximately 287 in 2024, with their market estimated at $22 billion in 2025. Appliance, electronics and phone protection plans extend the model further. Their prices may appear modest beside a mortgage, but each is another recurring commitment competing with savings.
Credit supplies relief today by reserving part of tomorrow’s earnings. At the end of 2025, 4,336 FDIC-insured banks and savings institutions and 4,287 federally insured credit unions operated in the United States. Their combined reported net income was approximately $314.4 billion. Their activities include business lending and other services, so this cannot be presented as profit extracted exclusively from households. But it establishes the scale of the institutions through which families finance major purchases and manage shortfalls.
Mortgages require the same accounting discipline. The latest official dataset covered 4,782 institutions reporting 2025 mortgage activity. The Mortgage Bankers Association’s October 2026 forecast put that year’s single-family mortgage originations at approximately $2.1 trillion. The principal advanced is not lenders’ revenue. Interest, fees, servicing and loan-sale income are the relevant earnings streams. United Wholesale Mortgage, for example, originated $163.4 billion in loans in 2025 and reported $3.16 billion in revenue.
Paris (Imran Y. CHOUDHRY) :- Former Press Secretary to the President, Former Press Minister to the Embassy of Pakistan to France, Former MD, SRBC Mr. Qamar Bashir analysis : Two elections, separated by one week, could reshape the future of the Middle East. Israel votes on October 27; Americans elect Congress on November 3. Behind both contests stands the same question: has the war against Iran made ordinary people safer, or has it made their lives more expensive and their future more uncertain? For Donald Trump and Benjamin Netanyahu, the battlefield is becoming an electoral liability.
These are different elections with interconnected consequences. Netanyahu is fighting to retain the premiership; Trump is fighting to preserve Republican control of Congress. An Israeli defeat could dislodge one architect of confrontation. An American congressional reversal could constrain the other. Neither outcome guarantees peace, but together they could alter the political machinery sustaining this conflict. Iran, the country Washington and Israel sought to weaken, could consequently become a central factor in weakening their leaders’ domestic authority.
The military buildup makes that possibility urgent. Euronews reported on October 16 that the USS George Washington and USS George H.W. Bush were operating in the Arabian Sea, with the USS Theodore Roosevelt heading toward the region. Approximately 9,000 additional sailors and Marines were being dispatched, potentially bringing regional naval personnel above 20,000. DefenseScoop also reported an autonomous surface vessel deploying with Roosevelt’s strike group. The preparations give Washington the means to turn threats into action.
Trump’s promise of no attack before the midterms offers little reassurance while American strike capacity continues to grow. On October 8, he publicly tied his pledge to November 3. His record of reversals gives reason to question whether this is electoral caution, negotiating pressure or tactical ambiguity intended to keep Iran off guard. Tehran therefore has reason to judge Washington’s military preparations more seriously than its president’s assurances.
CNN subsequently reported contingency plans potentially involving the Massive Ordnance Air Blast bomb. Read alongside the naval deployments, such planning gives Trump’s declaration a disturbing significance: the pause could provide time to position forces while encouraging an adversary to lower its guard. A sudden strike before the election could then be defended as deliberate deception. The political calendar shapes the danger; it does not reliably determine when that danger might materialize.
For Americans, the connection between foreign policy and household hardship is becoming difficult to ignore. Trump campaigned on restoring affordability. The BBC account places his approval near 37 percent and describes gasoline reaching approximately four dollars following disruption to Middle Eastern energy supplies. War reaches voters through fuel pumps, transport charges and household budgets. Presidential declarations of strength offer little comfort when families experience that strength as another expense they cannot avoid.
Republican vulnerability is acute in the House of Representatives. All 435 seats face election, and the governing majority is narrow. The Senate presents Democrats with a harder challenge: Republicans hold 53 seats, against 47 Democrats and aligned independents. Democrats therefore need a net gain of four for an outright majority. A national mood hostile to Trump creates opportunities, but individual candidates, turnout and state loyalties will decide whether discontent becomes congressional power.
History reinforces Republican vulnerability. The president’s party lost House seats in 20 of the 23 midterms from 1934 through 2022. Trump lost 41 in 2018, although Republicans gained Senate seats. Presidential unpopularity can punish the governing party without producing identical verdicts in both chambers.
Why would a Democratic victory matter to Iran? Congress controls appropriations and can attach restrictions to funding, investigate military decisions and challenge the legal basis for hostilities. A hostile House could make financing an extended campaign considerably more difficult. Democratic control of both chambers would strengthen that pressure. The essential question would become whether legislators actually use these powers, rather than merely expressing dissatisfaction while approving the resources that keep military operations moving.
Yet an electoral defeat would not immediately immobilize Trump. The new Congress takes office on January 3, 2027, leaving an interval after November’s vote. Trump could therefore confront a future Democratic majority with military decisions already taken. Congressional checks would remain significant, but their timing matters: an election that promises restraint could be followed by escalation before that restraint becomes effective.
In Israel, Netanyahu confronts a different version of the same reckoning. A leader who has built his authority around security must answer whether successive wars have delivered it. Households also judge the cumulative burden of expensive essentials and prolonged mobilization. These pressures do not require an economy in collapse to become politically powerful. Families can hear reassuring national statistics and still conclude that their own lives have become harder, less predictable and less secure.
The electoral arithmetic offers Netanyahu little comfort, although it leaves room for survival. An October 15 Times of Israel report put Gadi Eisenkot’s Yashar party at 26 seats and Likud at 20. Its poll projected 54 seats for the Jewish opposition bloc and 49 for Netanyahu’s camp, both below the conventional 61-seat majority in the 120-seat Knesset. Other surveys differ. The broad warning is uncertainty: dissatisfaction with Netanyahu has yet to produce an assured alternative government.
That uncertainty is central to his survival. Israel’s Basic Law provides for an outgoing government to continue until a successor is constituted. Netanyahu could therefore fail to secure a fresh majority yet remain prime minister during coalition negotiations or another electoral cycle. Political deadlock can prolong incumbency. An opposition that wins more seats but cannot assemble a government may discover that an adverse verdict against Netanyahu is insufficient to remove him.
His legal exposure adds another dimension. Netanyahu faces domestic corruption proceedings and an International Criminal Court arrest warrant issued in November 2024 concerning alleged war crimes and crimes against humanity. A warrant is not a conviction. Nor does losing office automatically produce arrest. Nevertheless, a weakened Netanyahu could face greater diplomatic isolation. Reduced American protection might make international cooperation with the Court politically easier, although enforcement depends on states, legal obligations and where he travels.
Still, voters have an opportunity to interrupt the assumption that military dominance entitles leaders to unlimited political patience. Americans and Israelis will vote for different institutions, but both can demand an accounting of promises, costs and results. Neither electorate controls the region; both can influence governments whose decisions reach far beyond their borders.
This is the story of two elections whose consequences will travel well beyond two countries. Iran may emerge as the issue that helped weaken the leaders who pursued war against it. The hopeful outcome is restraint, accountability and renewed diplomacy. The darker outcome is escalation pursued before restraints take effect. These ballots could open a door to peace. The world must hope their answer arrives before another devastating round of war.


‘Great result for Canada’, says Carney as Alberta votes to reject separatism

Rare Earths: Pakistan’s Economic Part 2
Rare Earths: Pakistan’s Economic Part 1

New Chapter for Dragon Boating in Punjab and Khyber Pakhtunkhwa Provincial associations officially set up with sights locked on national competitions and international representation.

South Korea’s Yoo Useong Steps Onto the Global Strongman Stage as World Strongman Federation Professional Athlete

A Survey of Mata-E-Zeest


-
 Pakistan News2 weeks ago
New Chapter for Dragon Boating in Punjab and Khyber Pakhtunkhwa Provincial associations officially set up with sights locked on national competitions and international representation.
-
 Sports4 months ago
South Korea’s Yoo Useong Steps Onto the Global Strongman Stage as World Strongman Federation Professional Athlete
-
 Art & Culture1 year ago
A Survey of Mata-E-Zeest
-

 Europe News2 years ago
Chaos and unproven theories surround Tates’ release from Romania
-

 American News2 years ago
Trump expands exemptions from Canada and Mexico tariffs
-

 Art & Culture2 years ago
Will Snow White be a ‘victim of its moment’? How the Disney remake became 2025’s most divisive film
-

 American News2 years ago
Trump Expels Zelensky from the White House
-

 Entertainment2 years ago
Champions Trophy: Pakistan aim to defend coveted title as historic tournament kicks off today